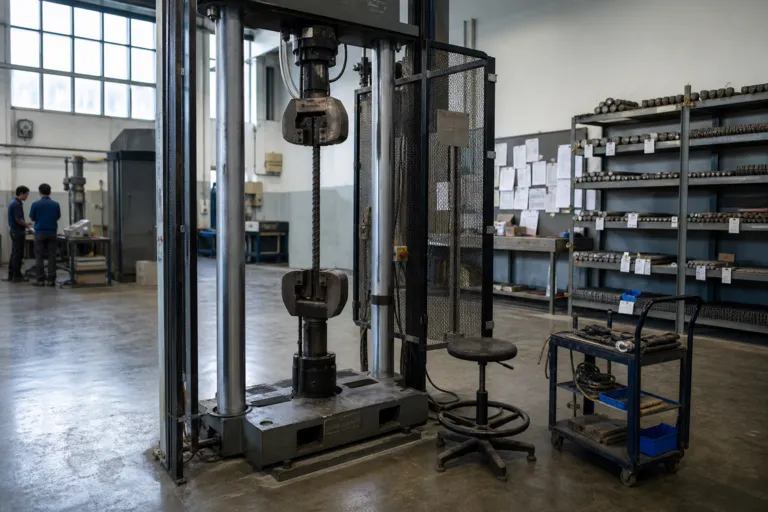
Singapore’s compliance economy is already large and structured. In 2026, the country’s Testing, Inspection, and Certification (TIC) market is valued at USD 1,795.8 million and is projected to reach USD 2,095.9 million by 2031, reflecting a CAGR of 3.14% over 2026–2031. That steady demand matters for construction because rebar quality assurance sits inside the broader logic of documentation, inspection, and certification that owners and contractors must manage. When the industry talks about a Singapore rebar testing reform in 2026, the key business question is not just technical compliance. It is whether upstream proof can reduce repetitive downstream checks, shorten administrative cycles, and make procurement decisions easier to defend during audits and project handovers.
International context also signals why rebar compliance is a persistent pressure point. A global rebar market forecast expects expansion from $160.088 billion in 2021 to $277.473 billion by 2033, with a CAGR of 4.69%. That backdrop does not describe Singapore specifically, but it helps explain why product variants, sourcing routes, and verification expectations keep evolving across regions. For a city-state that imports and coordinates complex supply chains, a reform that emphasizes upstream testing and clearer documentation could be used to simplify downstream site-level routines. In practice, that could mean fewer duplicated steps when material has already been validated earlier in the chain, and fewer disputes about which documents prove compliance for which batches.
Why “Upstream” Compliance Fits Singapore’s Broader Policy Direction
Singapore has already shown how benchmark-and-certification systems can shape procurement behavior in building materials. In February 2026, a new benchmark for concrete carbon intensity was launched, covering 68% of supply. The same discussion notes concrete’s upstream emissions are estimated at 3.7 million tonnes of CO₂e—around 6% of national emissions—and that most emissions occur outside Singapore’s borders, in imported materials and regional supply chains. Rebar is not the same material, and no rebar emissions data is provided here. But the pattern is instructive: when the key impacts and risks sit upstream, the most scalable controls often start upstream too. A rebar testing reform framed around earlier validation and stronger traceability could align with that ecosystem approach.
Cost sensitivity is also pushing Singapore markets toward automation and better operational design, which strengthens the case for less repetitive compliance work. In waste management, for example, rising operating costs—fuel, labor, and carbon taxes—are nudging the market toward automation, data-driven route optimization, and integrated processing complexes. The same report states the Singapore Waste Management Market is expected to grow from USD 1.34 billion in 2025 to USD 1.4 billion in 2026 and reach USD 1.73 billion by 2031, at a 4.35% CAGR over 2026–2031. This is not construction testing. But it illustrates a consistent national theme: when compliance and operations get more expensive, buyers look for systems that reduce manual handling, standardize proof, and improve predictability.
For contractors and suppliers, the practical implication of a Singapore rebar testing reform 2026 discussion is how it could change what gets verified, when, and by whom. In TIC, demand in Singapore is described as reflecting consistent need for quality assurance and compliance services. That suggests reforms may not eliminate testing work so much as reallocate it across stages—potentially shifting more value to early-stage validation, batch documentation, and standardized certification packages that reduce rework later. If procurement can rely on clearer upstream evidence, project teams may spend less time chasing fragmented records and repeating checks at multiple points. The result would be a different compliance workflow: fewer disputes about sufficiency of proof, smoother acceptance routines, and documentation that is easier to reuse across projects.
What is the size of Singapore’s TIC market in 2026, and why does it matter for rebar compliance?
What benchmark precedent suggests Singapore can influence material practices through measurement?
What does the sources’ construction-material context say about upstream impacts?
How does the global rebar market outlook relate to compliance discussions in Singapore?
What question should firms ask about Singapore’s 2026 rebar testing reform as a buyer of TIC services?