
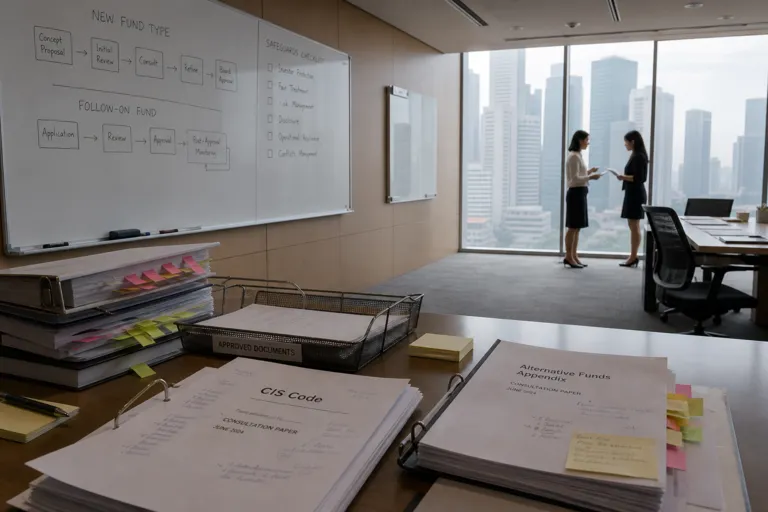
On 9 July 2026, the Monetary Authority of Singapore (MAS) published a consultation paper proposing amendments to the Code on Collective Investment Schemes (CIS Code), the rulebook governing retail unit trusts and ETFs authorised for sale in Singapore. The core idea is to widen retail investment choice without lowering baseline standards. MAS proposes a new “Alternative Funds Appendix” to sit alongside the existing code, giving a clearer route for fund types that do not fit today’s investment guidelines. MAS also emphasised that core requirements would continue to apply, including asset safeguarding and liquidity standards, along with governance and fair-dealing expectations for fund managers and distributors.
The consultation is an early-stage proposal, not a finished rule change. MAS is seeking feedback until 10 August 2026 before deciding how to proceed. Still, the direction is clear: MAS wants a more streamlined process that can accommodate a wider range of innovative fund structures, while adding guardrails tailored to the risks of each new fund type. MAS said new fund types would face requirements specific to their unique risks, plus enhanced disclosure obligations to help investors make informed decisions. In parallel, managers and distributors would remain responsible for ensuring products are suitable for their target customer segments and that investors receive clear and timely information.
Why the Three-Week Target Could Matter for Retail Choice
Speed is the point most likely to change how quickly investors see new offerings. MAS said it could take about three months to determine the necessary safeguards for most new fund types. After those safeguards are established, subsequent funds of the same type could be authorised within three weeks if they meet the prescribed requirements. MAS linked this three-week goal to an existing “21-day processing time” that applies to authorisation applications for collective investment schemes that do not have novel features with a material impact on investors. If implemented, this faster pathway could reduce time-to-market for follow-on launches and give fund managers clearer expectations when designing similar products.
The Alternative Funds Appendix is also meant to make the regulatory perimeter easier to navigate for innovation. MAS stated it has received market interest to offer two new retail fund types: futures-based single-commodity funds, and a wider array of single-country government bond funds. These examples illustrate the type of products that may not always fit neatly under existing investment guidelines. Under the proposed approach, MAS could adjust existing investment requirements and accommodate a broader range of fund structures offered to retail investors, while still differentiating innovative funds from traditional funds such as established equity funds or bond funds that are subject to diversification requirements.
This proposal also sits within a broader 2026 sequence of retail market reforms. The consultation follows changes announced by MAS in May to streamline the Complex Products framework and revise Product Highlights Sheets. Taken together, the direction supports product innovation while keeping investor protection in view through disclosures, safeguarding and liquidity standards, and accountability on product design and distribution. For anyone tracking the topic of MAS faster approval of new fund types in 2026, the key near-term milestone is procedural rather than commercial: the consultation closes on 10 August 2026, after which MAS will decide whether, and how, to implement this faster, appendix-based approach.
What is MAS proposing with the Alternative Funds Appendix?
How fast could follow-on funds be authorised under the proposal?
How long would MAS take to set safeguards for most new fund types?
Which new retail fund types has MAS said it has seen market interest in?
What does the MAS faster approval of new fund types in 2026 depend on next?