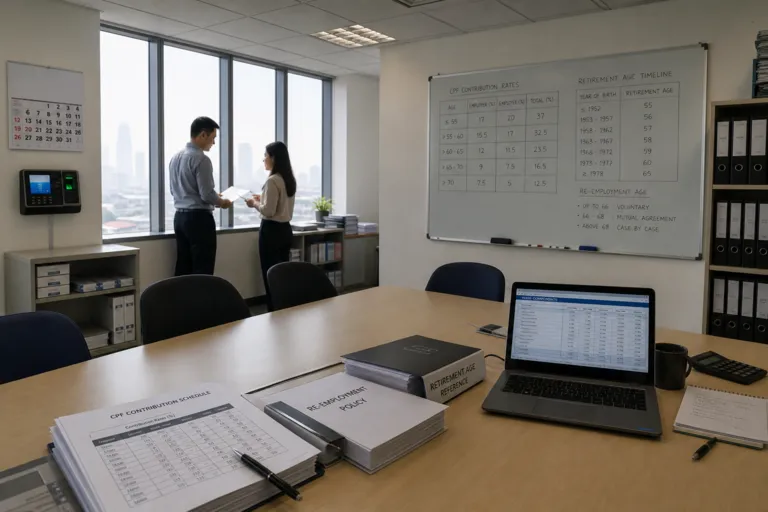
Singapore’s retirement and CPF landscape moved in tandem in 2026. The statutory retirement age rises from 63 to 64 on 1 July 2026, and the re-employment age goes from 68 to 69 on the same date. At the same time, the CPF Ordinary Wage (OW) monthly salary ceiling rose from S$7,400 to S$8,000 from 1 January 2026. CPF LIFE payout eligibility stays at 65, so the planning challenge is often the period between work decisions, CPF accumulation, and when payouts begin.
The higher OW ceiling is straightforward: more monthly salary can be subject to CPF contributions. For a Singapore Citizen or PR aged below 55 earning S$8,500 a month, the ceiling shift means S$600 more of salary attracts CPF. At the combined 37% rate, that equals S$222 more in CPF contributions each month, split as S$120 from the employer and S$102 from the employee. Another example shows an S$8,000 monthly salary leading to an extra S$222 into CPF each month, or S$2,664 a year, due to the ceiling change. This can modestly reduce take-home pay now, while increasing long-term CPF accumulation.
What 2026 Means for Older Workers and Retirement Targets
For older workers, the policy signal is also explicit: work longer if you can, and save more while you do. From 2026, CPF contribution rates for workers aged above 55 to 65 increase by 1.5 percentage points. Another breakdown states workers above 55 to 60 have a total contribution rate of 34%, while those above 60 to 65 sit at 25%. The additional contributions are credited to the employee’s Retirement Account (RA), up to the Full Retirement Sum (FRS). That matters because the retirement sums used at age 55 were also updated for the cohort turning 55 in 2026: the Basic Retirement Sum (BRS) is S$110,200, the FRS is S$220,400, and the Enhanced Retirement Sum (ERS) is S$440,800, set at 4× the BRS.
These shifts land in a CPF system that is already large and widely used. As at March 2026, Singapore’s 4.3 million CPF members held S$677 billion in their accounts, with about 2.2 million described as active members. SmartWealth’s analysis (as at 31 December 2025) puts the average CPF member’s net balances at S$154,829, with averages peaking at S$315,123 for ages 51 to 55. It also reports that 73.4% of active members reached their Required Retirement Sum at 55 in 2025, up from 63.6% for the 2020 cohort. These figures help frame why ceiling and contribution changes can compound into meaningful differences over time.
Retirement income expectations are another reason the 2026 updates draw attention. CPF LIFE recipients received an average of about S$676 a month in 2025, which SmartWealth links to smaller retirement sums from earlier cohorts, compared with an estimated S$1,780 for the 2026 FRS cohort (CPF LIFE Standard Plan estimate). In 2025, CPF credited members S$23.6 billion in interest, and voluntary top-ups reached a record S$10.4 billion. Seen together with the statutory shift to age 64 and re-employment to 69, the Singapore CPF changes tied to retirement age in 2026 emphasize a longer accumulation phase and higher formal targets, even as payout eligibility remains 65.
What changed in Singapore’s CPF Ordinary Wage ceiling in 2026?
How did Singapore’s retirement age and re-employment age change in 2026?
How much more CPF can flow in each month because of the higher ceiling?
What are the 2026 CPF retirement sums for someone turning 55 in 2026?
How do the Singapore CPF changes and retirement age in 2026 affect planning for payouts?